Disclaimer
This article analyzes market positioning using data derived from the CME Group QuikStrike Tool strictly for educational, informational, and analytical commentary under the doctrine of Fair Use. The content presented herein is Not Financial Advice, investment guidance, or a solicitation to buy or sell any currency or derivative contract. Foreign exchange and futures trading involve significant financial risk and may not be suitable for all investors. Always exercise prudent risk management and consult a licensed financial advisor before risking capital.
Introduction
Navigating the foreign exchange markets successfully requires peering behind the curtain of retail chart patterns into the realm of institutional order flow. While retail technical analysis often focuses purely on lagging indicators, professional market participants track institutional commitments, liquidity sweeps, and options positioning.
For the EUR/USD (6E) currency pair, combining Smart Money Concepts (SMC) with institutional derivatives analytics creates an exceptionally powerful trading edge. While price action reveals where liquidity resides on the price chart, exchange options metrics—such as Open Interest, Delta-hedging obligations, Gamma clusters, and Vega risk—reveal where market makers and large institutions are financially committed to defending the market.
This publication breaks down the latest CME Group options positioning, establishes the critical institutional support and resistance boundaries, and outlines a multi-timeframe SMC execution strategy.
Technical Analysis of Options Data
A thorough examination of the currency options chain across multiple metrics (Open Interest, Volume, Delta, Gamma, Vega, Theta, and Churn) provides an empirical map of institutional positioning:
- Volume Put/Call Imbalance (P/C Ratio: 1.97):
- Total Put Volume reached 19,748 contracts, compared to 10,022 Call contracts, yielding an institutional Put/Call volume ratio of 1.97.
- Traded put activity was virtually double that of calls. In exchange-traded currency options, heavy put trading combined with positive open interest growth indicates aggressive institutional put writing (selling downside protection to capture decay) rather than speculative buying.
- Open Interest (OI) & Structural Put Walls:
- Total Put Open Interest stands at 230,499 contracts versus 220,809 Call contracts (OI P/C ratio of 1.04).
- Put open interest is densely concentrated directly beneath current market pricing (1.1409 – 1.1436), creating a thick floor of institutional bids.
- Delta Exposure & Market Maker Hedging:
- Delta-weighted Open Interest (OI × Delta) reveals massive negative delta exposure centered at key put strikes.
- To maintain delta neutrality, options market makers must dynamically buy underlying futures contracts as prices approach these levels, creating automated buying support (Dealer Long Delta / Short Gamma absorption).
- Gamma Clustering (GEX) & Volatility Suppression:
- The monthly contract exhibits a peak Gamma concentration of over 232,000 Gamma, centered at the At-The-Money (ATM) boundary.
- High positive dealer gamma suppresses volatility, turning these strike zones into market magnets and strong structural floors.
- Vega Exposure & Long-Dated Institutional Hedging:
- Longer-dated expirations (17 DTE to 40 DTE) show substantial Put Vega accumulation, indicating that large institutions have parked their macro downside insurance at deep structural base levels.
- Institutional Churn Rate (Conviction Metric):
- Analysis of the Churn ratio reveals retention rates as high as 95% on primary defensive strikes. This confirms that traded volume was not day-trading noise, but permanent, high-conviction institutional positions held overnight.
Top 3 Support/Resistance Points
Based on institutional order flow, gamma clustering, and open interest distribution, the key levels defining market structure are:
1. Immediate Active Support: 1.1425
- Supporting Data:
- ~1,000+ Traded Gamma per Pip across short and intermediate weekly contracts.
- +1,210 contracts added in the near-term 3-DTE expiry (WE2V0).
- Churn retention rate of 75%–80%, reflecting high institutional holding.
- Reasoning: Situated just 11–14 pips below current market pricing (1.14365 reference / 1.1409 futures), this is the front line of defense. Market makers have accumulated substantial short-dated gamma here, ensuring rapid dynamic buying response on any initial intraday dip.
2. Primary Institutional Wall (The Core Anchor): 1.1400
- Supporting Data:
- 10,770 Put contracts in the monthly expiration (EUUV0) alone.
- -5,012 Delta Exposure—the largest single delta concentration across the entire options chain.
- 232,000+ Put Gamma peak node.
- Reasoning: 1.1400 is the central institutional battleground. Because of the sheer magnitude of delta and gamma exposure, options market makers are forced to aggressively hedge and absorb sell orders at this boundary. It functions as the primary macro support floor for the entire cycle.
3. Shock-Absorber Defense: 1.1375
- Supporting Data:
- Single largest 1-DTE volume and OI spike: 1,510 traded contracts and +1,429 fresh puts added.
- 95% Churn Rate (the highest conviction retention on the board).
- 64,400+ 1-DTE Gamma with steep Implied Volatility (IV) smile skew.
- Reasoning: In the event of a temporary liquidity sweep below 1.1400, 1.1375 acts as a fortress. Option writers who wrote over 1,400 contracts expiring in under 24 hours have maximum financial incentive to prevent this level from being breached, making it a prime institutional bounce zone.
(Note: Major macro structural base support remains firmly anchored between 1.1300 and 1.1250, supported by over 4,000 traded volume contracts and long-dated 40-DTE vega accumulation).
Key Overhead Resistance (Call Walls):
- 1.1450 & 1.1500: Highlighted by massive Call concentrations (11,295 Calls at 1.1450 and 10,039 Calls at 1.1500), marking the upper ceiling of the current expected trading corridor.
Data Summary Table
The table below summarizes the quantitative derivatives metrics extracted across the options chain:
| Strike Price | Primary Metric / Volume | Delta / Gamma Profile | Position Type | Institutional Role & Market Impact |
|---|---|---|---|---|
| 1.1450 – 1.1500 | 11,295 & 10,039 Calls | Peak Call Gamma & Volume | Major Overhead Resistance | Primary overhead ceiling; heavy call writing caps short-term upside expansion. |
| 1.1425 | 1,210 Vol / 1,740 OI | ~1,000 Gamma/Pip (75% Churn) | Immediate Active Support | First-line dynamic buffer; activates rapid dealer hedging on intraday pullbacks. |
| 1.1400 | 10,770 Monthly Put OI | -5,012 Delta / 232k Gamma | Primary Institutional Wall | Central market anchor; high-density delta absorption floor preventing structural breakdown. |
| 1.1375 | 1,510 Vol / +1,429 OI Change | 95% Churn / 64.4k 1-DTE Gamma | Shock-Absorber Cushion | High-velocity bounce zone; short-term options writers aggressively defend premium decay. |
| 1.1300 – 1.1250 | 3,600+ Put OI / 4,000+ Vol Spike | 170+ Longer-Dated (40 DTE) Vega | Macro Structural Base | Deep institutional safety net; heavy macro hedging base floor for multi-week trend integrity. |
My Technical Outlook & Trading Strategy
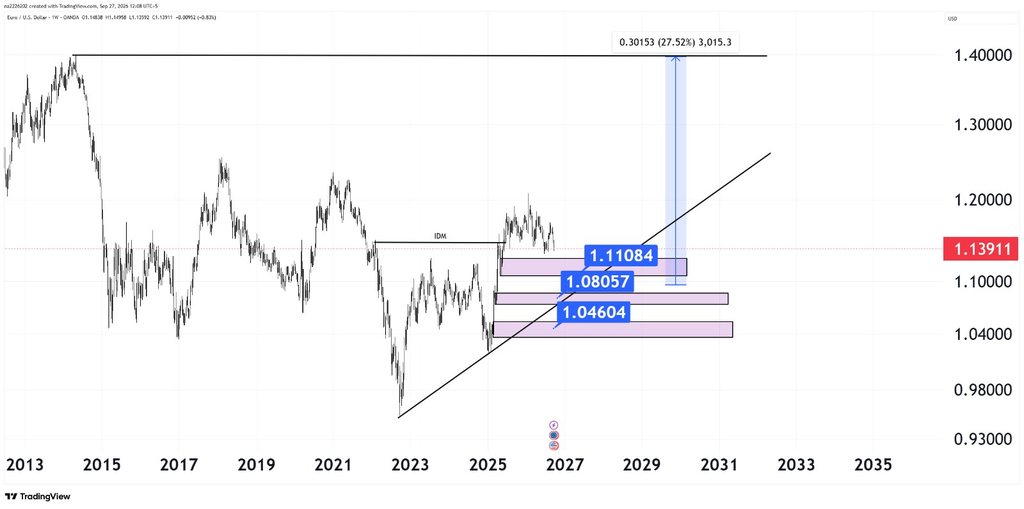
1. Higher-Timeframe Structure: The Weekly Bullish Trend
A top-down analysis begins on the weekly timeframe, which provides the macro narrative and prevailing order flow:
- Market Behavior: The weekly trend remains clearly oriented to the upside, displaying consistent higher highs and higher lows.
- Ascending Trendline Confluence: A well-defined ascending trendline underpins this price action, providing visual confirmation of sustained buying interest across multiple weekly cycles.
Trading in alignment with this higher-timeframe trend significantly tilts the probability in favor of long positions, provided entry execution is handled with precision.
2. Smart Money Concepts (SMC): Inducement & Key Demand Zones
- Inducement (IDM) Formed: Under the SMC framework, liquidity drives price movement. Price has recently created and swept Inducement (IDM) on the higher timeframe. Taking out internal liquidity (IDM) signals that smart money has cleared temporary retail liquidity to fuel the next major expansion leg. The broader target remains the creation of a new swing high.
- The Three Institutional Order Blocks (OBs): Beneath current market pricing lie three distinct Weekly Order Blocks (Demand Zones). These zones serve as institutional “fuel tanks”—areas where substantial buy liquidity resides to propel price back into the prevailing uptrend.
3. Precision Entry Strategy: 1-Hour & 15-Minute Confirmation
One of the most critical principles of professional trading is never entering blindly simply because price touches a higher-timeframe order block:
- Do Not Front-Run: Limit orders placed directly at higher-timeframe order blocks expose traders to severe drawdown if momentum cuts through the zone.
- Step-Down Process: Once price mitigates a weekly order block, switch immediately to lower timeframes—specifically the 1-Hour (1H) and 15-Minute (15M) charts.
- Waiting for Lower-Timeframe Inducement: Look for market structure shifts on the lower timeframe, including:
- A lower-timeframe Change of Character (CHoCH).
- A clear sweep of lower-timeframe Inducement (IDM).
- A confirmed shift in momentum showing buyers stepping in.
Entering on confirmed lower-timeframe logic ensures that risk parameters are tightly defined, stop-loss distances are reduced, and entry occurs with empirical market confirmation rather than guesswork.
4. Institutional Confluence & Macro Risk Protocols
- Derivatives Alignment: CME Group options positioning confirms a strong bullish baseline, with significant Put Open Interest and positive dealer hedging buffers concentrated beneath current spot levels.
- Macro Event Caveat: Market direction can change rapidly upon high-impact macroeconomic data. Major economic releases (such as Central Bank rate decisions, Non-Farm Payrolls, and CPI reports) carry the power to invalidate technical structures instantaneously.
- Stop-Loss Discipline: Always define your invalidation point before entering any position. A hard stop-loss is mandatory to protect capital against sudden volatility spikes. Only execute trades when your technical setup, lower-timeframe confirmation, and economic calendar conditions fully align.
SMC Trading Strategy & Execution Matrix
The following operational framework outlines the step-by-step criteria required for trade validation and execution:
| Step / Phase | Timeframe | Technical Trigger & Condition | Strategic Purpose & Execution Action |
|---|---|---|---|
| Phase 1: Macro Trend | Weekly (1W) | Ascending Trendline & Higher Highs/Lows | Confirms prevailing bullish trend; establishes long-only trading bias. |
| Phase 2: Liquidity Identification | Weekly (1W) | Inducement (IDM) Sweep + 3 Order Blocks | Identifies structural fuel; marks high-interest demand zones for price mitigation. |
| Phase 3: Zone Mitigation | Weekly (1W) | Price taps Weekly Order Block (Demand Zone) | Do not enter blindly. Switch immediately to 1H and 15M execution charts. |
| Phase 4: Lower-Timeframe Shift | 1-Hour (1H) | Change of Character (CHoCH) / Break of Structure | Validates that institutional buyers are defending the higher-timeframe zone. |
| Phase 5: Execution Trigger | 15-Minute (15M) | Sweep of 15M Inducement (IDM) into 15M OB | Enter long trade on confirmation. Place hard Stop Loss below the structural low. |
| Phase 6: Macro Risk Check | Macro / News | High-impact events (NFP, CPI, Central Bank rates) | Close or de-risk positions before major volatility events; respect invalidation. |
Conclusion
EUR/USD presents an exceptionally clean technical and quantitative alignment. Higher-timeframe market structure remains structurally bullish, smart money inducement mechanics indicate an impending push toward new highs, and institutional derivatives data from the CME Group confirms a solid defense wall between 1.1425 and 1.1375.
By combining weekly demand zones with disciplined 1-Hour and 15-Minute lower-timeframe execution, traders can avoid premature entries and trade in harmony with smart money order flow. Maintain strict stop-loss discipline, respect incoming macroeconomic catalysts, and let systematic confirmation guide your trading decisions.